Marquis Who’s Who, Honors Vern Hayden
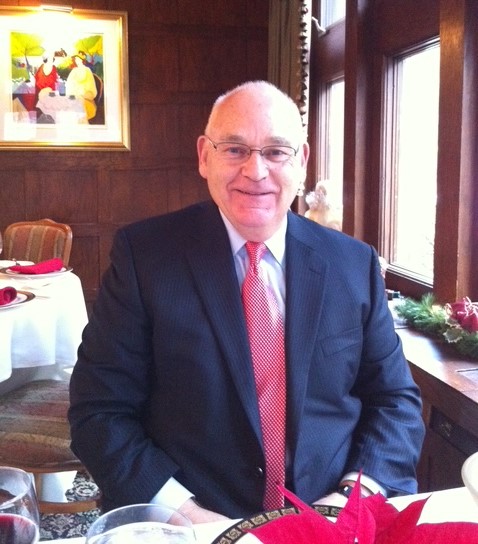
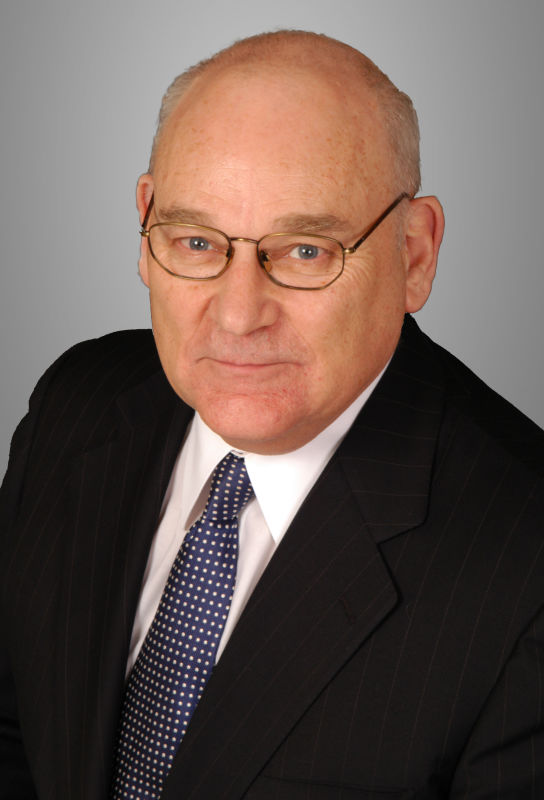
Vern Hayden is honored for his expertise in Financial Planning by Marquis Who’s Who which has chronicled the lives of the most accomplished individuals and innovators from every significant field and industry.
Yahoo Finance published this press release on August 20, 2026 – Marquis Who’s Who Honors Vern Hayden for Expertise in Financial Planning
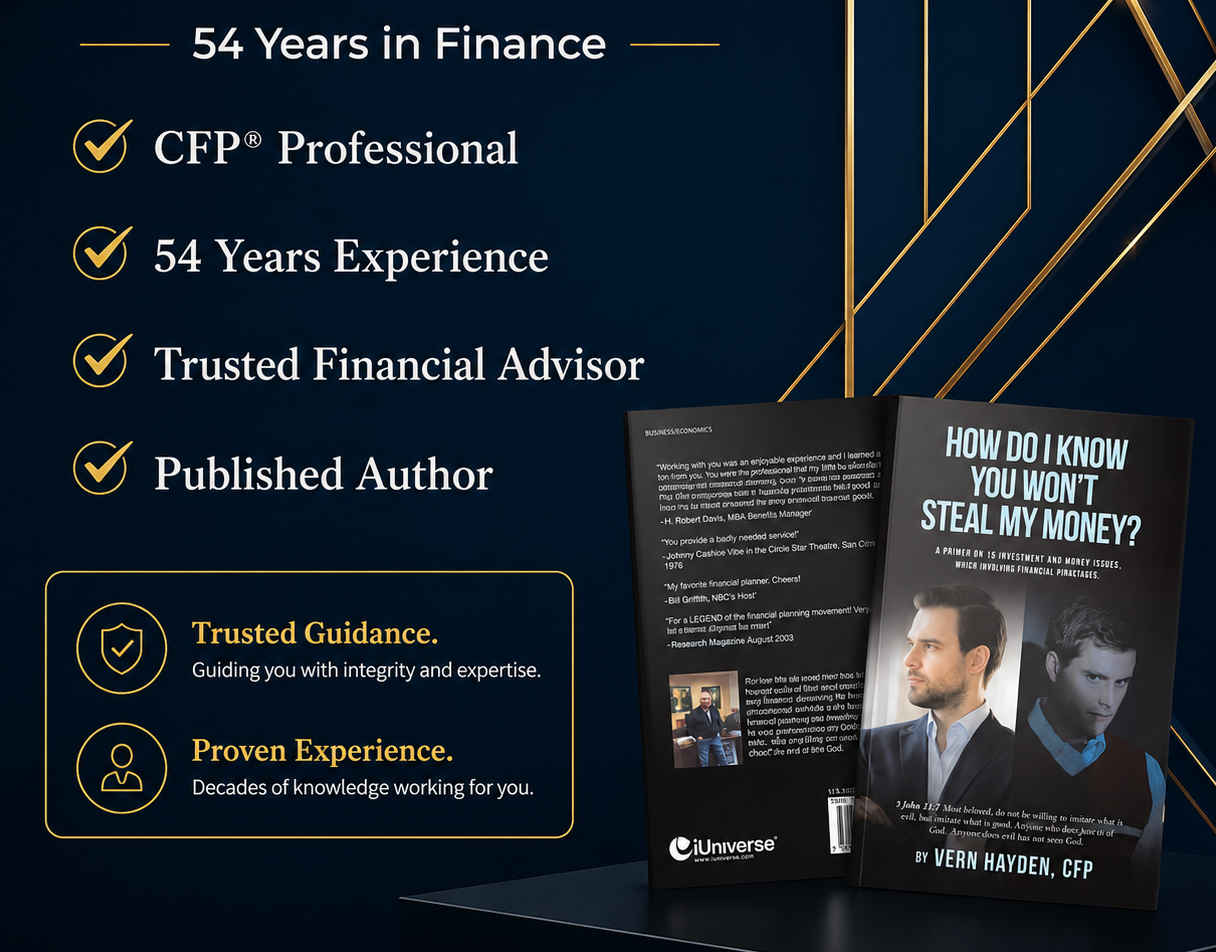
Get a copy of my new book “How Do I Know You Won’t Steal My Money” by going to the Buy The Book webpage.
Knowing Risk is Essential for Successful Investing
Because I have done financial planning and investment management for decades some people assume I know more than I do. I try my best to control that mistaken perception by first explaining, I am not an economist, and secondly, I cannot know for sure what will happen in markets.
However, I have been known to make predictions based on market trends I believe have an abnormally high risk. And knowing the inherent risk factor is crucial in determining where and when to invest your money.
For instance, in December of 1999 during an interview with Bill Griffith on CNBC, I suggested people get out of the market, for at least the first 6 months of 2000, in order to play it safe and minimize risk. No one heard me; my advice went unheeded, and investors experienced large losses.
At that time “tech stuff” was sky high but at the same time “Leverage Investing” was also very high, i.e. investors were borrowing money in the form of loans, securities, capital or other types of assets in order to invest more, which can be very good…………until the return becomes less than the cost of borrowing.
And at that time, my investment territory of mutual funds was also unsustainably high. So, I pulled in my horns and focused on more of a conservative, less risky strategy espoused by value managers like Jean Marie Evielard of First Eagle Investments and Steve Romick of First Pacific Advisors. And both had funds that were up and stable during the crisis as a result.
Looking back, I wasn’t trying to pass myself off as a market guru but simply explaining that I was not, shall we say, immune to knowing when there was trouble brewing on the horizon.
An old saying applies here, “A wise man sees trouble coming from afar and hides himself but the unwise pass on and are punished”
For example, right now I see a lot of trouble brewing. Case in point; America’s $40 trillion plus debt triggers over a trillion dollars of yearly interest payments, and to me this sends up a red flag. And foreigners don’t want to buy our treasuries like they used to; this also causes great pause in my mind—where does this end for the financial investor over the next few years?
Now consider that Japan owns more US Debt than any other country—currently $1,078 billion. And most foreign banks are loading up on Gold. Plus, Social Security is in big trouble; a 25% cut will happen in less than 10 years if our impotent politicians don’t remedy it first. And is that even possible?
Who Owns the $39T US Debt? Top Holders Breakdown (2026)
And then as if that isn’t enough, there’s the current political mess. And what if Trump losses both the House and Senate in the midterms, if so, we won’t see much positive investment news but instead a constant warring against Trump for the last two years of his term.
Then there is the whole question of Artificial Intelligence. It is powerful and that makes it dangerous. As a result, several unheard-of companies have sprouted up with very little economic sense, much like what happened during the dot com internet crises of 2,000. If AI is not in a bubble of some kind, it is on a collision course with one. Either way I predict the end result will not be good.
Do I see and feel trouble ahead? YES! There will be a significant market crash or in more polite terms, an “adjustment”. How much of an adjustment? I don’t know, and I certainly do not know the date, and frankly, no one does.
However today I am six months from being 90 yrs. old and fairly sure it will happen in my lifetime…….and I am not in great health. So optimistically, let’s say for the record, in the next five to ten years it will be very challenging for investors to make correct decisions investing money, to say the least.
Another old saying comes to mind, “Old warriors know to hold back and wait for the best time to enter the fray…if they enter at all.”
As I write this, my mind goes back to one of my favorite investment guys, Robert Rodriquez. He was president of First Pacific Advisors for 25 years as well as a fund manager. He forecast the dot.com crash and the 2008-2009 financial crisis. He also exposed the bond rating agencies as being inaccurate in the 1990’s.
He retired in 2016 and got out of the stock market. He felt the dollar and other currencies were going to get hammered in the next decade, relative to Gold. He currently has invested 30% in Gold and 85% in hard assets like rare coins and high-end real estate. Having spent 7,000 to 10,000 hours researching these investment areas and opportunities, Robert has taken a very conservative much less risky approach to investing his money.
All this information is from a December 23, 2018, published interview by Think Advisor. I knew Bob personally and was on CNBC with him. Bob Rodriguez: Recent Market Turmoil a ‘Preamble’ to Bigger Crisis
I can tell you this is a time to be very conservative and follow the principles outlined in my book. Don’t trust until you verify. This requires that you learn the basics of money management and financial investing. Knowing risk is essential for successful investing, and it takes experience to see the risks.
In my book, I’ve broken down what you need to know in 29 short concise chapters, designed to enhance your ability to recall what you’ll need to verify each step in the process. In the end, your trust will be established and grounded firmly in truth.
Priceless.
Go to my “Buy the Book” page, click on the link and choose either the softcover for $12.99, the hardcover for $31.99 or the E-Book for $4.99. No matter where you buy my book, you’ll pay the same price but through iUniverse I receive a significantly higher royalty so please buy, as the expression goes, “In House”.
Thank you.
Annuities Can Be an Essential Element of a Good Financial Investment Plan
This blog post is all about keeping your money alive and kicking; thriving while you get older than you thought you would ever be.
This hit home for me when my dad died at age 72. This caused me to believe when I was in my sixties that I would be gone by 75. But here I am today just 6 months from 90. How did that happen? It certainly was not because I eat right because I don’t. I still eat a Snickers and a Butterfinger candy bar once a week, and my ice cream has to have some caramel on it, and I definitely consider chocolate chip cookies almost a daily necessity.
I am not bragging here but instead just saying how lucky I am. Lucky in the sense that I would have died but for the fantastic doctors who kept me alive. For example, in 2006, I had open-heart quadruple bypass surgery. And anyone who also had this medical procedure, knows it’s a “let me outta here” type experience.
Research statistics indicate that of the four million or so people reaching the age of 65 this year, most, if not all of them, will try to figure out if they have enough money to live on until the day of their death.
Few people know when they will die. As they look at the research, they are told that if you are 65, depending on numerous variables, you might live to 78. And if your 75 you might just make it to 90……maybe, that is, if you’re lucky like me. I’m being optimistic here with six months to go.
So the questions therefore are, how much income will I have? At what rate will I or should I spend it? And how much can I earn through a good investment plan?
It is at this point of reasoning that almost all people realize, and are convinced, that they need the right kind of financial planner to address these questions and provide financial guidance.
In my new book, “How Do I Know You Won’t Steal My Money” I addressed these questions in chapter 24.
Over the past 56 years I have come to know a lot of financial planners. I was Chairman of the College for Financial Planning and also on the Certified Financial Planner Board and the Financial Planners Association Board.
And as you might have already concluded, there are some bad CFPs, but then again, there are also many who are very good. When it comes to financial investment planning the most important step is the first one, which is to find a very good, well proven, highly experienced, truthful, honest, qualified, certified financial planner (CFP).
Today when people ask me to recommend a very good CFP, I always refer them to Bill Brancaccio CFP. He has lots of experience, very intelligent, and a good ‘people person’. I have introduced him to all my clients over the years, and everyone really likes him. He can be trusted hands down. Check out these search results Bill Brancaccio – Search
I also strongly recommend reading five short chapters 2-6 in my book. I am confident that you will gain a foundational background for understanding annuities.
Then read the Barrons article, “The 100 Best Annuities. How to Avoid Common Mistakes and Pick the Right One.” Published July24.2026 by Karen Hube – Link The 100 Best Annuities of 2026: How to Buy the Right One – Barron’s
One small example from the article. The current top three annual income guarantees for a person investing $200,000 at age 60, and then after ten years turning on the income stream at age 70, averages $33,702 annually. That becomes a wonderful supplement to social security.
This is not an easy decision for anyone to make on their own. So again, I emphasize, this very important decision needs to be made from within the context provided by a proven financial planner’s guidance plan.
I’ve always said that “Good Luck” doesn’t just fall out of the sky, but instead is created through intelligence, knowledge, and truth. I have based my career on this financial philosophy and look forward to addressing any questions you might have so please don’t hesitate to contact me. I will do my best to point you in the best direction possible.
Please feel free to use the CONTACT THE AUTHOR – Vern Hayden CFP webpage.
Simplicity is a Wonderful Thing
Simplicity is a wonderful thing when it comes to understand something, because it is easier to remember and implement effectively. When it comes to your money just remember three words: Save, Invest, and Insure. Those three words create a simple structure for you to implement to do everything important regarding your money and your future plans and goals.
1. SAVE
Saving some money does not mean depriving you of anything. It means you are allocating some money for future use. It will be like giving yourself a reward and a sense of fulfillment . Of course there are many possible reasons to save. You need to know why you are saving money. The “why” provides the incentive and motivation to do it. It is important to write down your “whys” and how much money you will need by a certain time. It isn’t just about traditional retirement or financial independence. It includes anything you want to accomplish in the future such as a car, a house, kids’ education, vacations and trips.
I wrote my first book, “Money: Use It or Lose It” in 1979. My friend, Fred, asked me for a copy. Fred was a good handball buddy and was a coach at a high school in Marin County, California. His wife was a school teacher at the same school. They had more than an ounce of discipline and decided to save her salary and live off of his salary. Today they have met all their financial goals and are more than financially independent. Everyone has to work out their own savings plan but any amount consistently saved over time will create a nice nest egg.
2. INVEST
Investing is not simple. In fact it is one of the most challenging and complex subjects there is. Very few people should try to do this on their own. A word of caution. If you are going to pay someone to help you then make sure they will represent you, and I’m not talking about an institution like a bank or insurance company.
You need to work with someone or some company that is independent and not connected to Wall Street or an insurance company. The best combination of professionals to use would be a CFA(Certified Financial Analyst) and CFP(Certified Financial Planner) who manage on a fee only basis.
In my book I refer to places to look for these professionals.
The subject reminds me of the two times I was on CNBC with Jack Bogle, the founder of Vanguard Funds and the father of index investing. In January 1,1989 Jack and I were sitting next to each other on the set at CNBC. We were taking calls from the public through two hosts.
Brenda Butner one of the hosts put me on the phone with a lady asking me where to invest $60,000 . After advising her that I would need to know a lot more about her situation before advising her but gave her the name of three excellent mutual fund managers.
Then Brenda tossed the question over to Jack. Jack said, “Yes we need to know more about you but you only need one fund, The Vanguard Total Stock Market Fund”. Jack and I represent two different investment philosophies. So goes the discussion between indexing and active management. The lady on the phone would do fine going either way.
To look for more information I refer you to my second book “Getting an Investing Game Plan” published by John Wiley and Sons in March 2003. There are still used copies, and e-book versions available online.
3. INSURE
Insuring is all about financial protection from disaster. Insure your car, your house, your business, jewelry. And your most important asset…yourself. You do this so it will not be counterproductive to saving and investing. This subject is covered in all three of my books,
Most people need help to do all this. You would be well served to use a Certified Financial Planner.